A budget reset is a 90-minute one-time setup followed by a 60-minute weekly cadence: anchor to one emotional reason, list every account and subscription, run a zero-based plan for the next 30 days, automate every fixed transfer, name three friction points, and schedule a weekly review. Systems beat income for predicting financial control.
Here is something the budgeting world does not say out loud often enough: the households that actually escape the debt cycle are not the highest earners. They are the ones with the cleanest systems.
Spirit Financial Credit Union’s 2026 debt-reset research lands on this exact finding, and once you see it, the whole frame around ‘I just need to make more’ starts to shift.
A budget reset is the 90-minute setup that gets those systems in place. Six steps. Done once. Followed by a 60-minute Sunday slot that keeps the whole thing honest. It is unglamorous. It is also the reason the 90 days after the reset feel measurably calmer than the 90 days before.
Here is how the work breaks down, and why each step lands where it does.
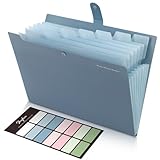
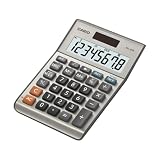
Recommended Tools for the Budget Reset
A short stack of physical anchors keeps the reset on track. The five recommendations are the ones most consistently mentioned in financial-counselling practice.



Recommended reads:
- How to Set Money Boundaries Without Guilt
- A Money Mindset Routine for a Calmer Start to the Day
- How to Start a Low Buy Challenge That Feels Sustainable
- How to Recover Financially Without Shame or Panic
- Financial Resolutions That Create Real Change With Money
Why Systems Beat Income
The Cycle of Reactive Spending
Households without explicit budget systems run on reactive spending. Income arrives, bills get paid, the remainder gets absorbed by whatever discretionary spending happens to come up. The pattern produces almost identical end-of-month outcomes regardless of income, because the reactive structure scales with whatever is available.
The Shift to Automated Systems
The shift that produces financial control is structural rather than financial. Automated transfers happen before the money becomes available for spending. Categories have explicit caps. Subscriptions get reviewed quarterly. The system removes most of the daily decision-making, which is where the leakage usually happens. The monthly money reset covers the zero-based budgeting framework that anchors the system.
Step One: Anchor to One Emotional Reason
Why the ‘Why’ Matters More Than the Number
Numerical goals lack the longevity to sustain the work across hard weeks. Emotional anchors do. The frame from 2026 financial-recovery research: tie the reset to one specific emotional outcome. Family stability. A planned house deposit. Less partner tension about money. The retirement that feels safe instead of theoretical.
How to Find the Anchor
One sentence. Specific enough to picture, simple enough to remember. ‘I want my kids to feel secure about household money.’ ‘I want to look at the credit card statement without flinching.’ ‘I want the partner conversation about money to stop ending in silence.’ Write the sentence at the top of the budget document.
Reread it at every weekly review. The journaling for emotional clarity guide covers the deeper writing practice for the harder versions of this work.
Step Two: List Every Account and Subscription
The Full Inventory
Most households do not know how many accounts they actually have. Checking, savings, joint, business, retirement, broker, app-based (Venmo, Cash App, PayPal). Plus credit cards. Plus subscriptions. The first step of the reset is one document listing all of them with current balances. The inventory usually surfaces two or three accounts the household had forgotten about.
The Subscription Audit
List every recurring charge. Streaming services. Software licences. Gym memberships. App subscriptions. Box subscriptions. The audit usually surfaces $80 to $200 per month of charges nobody is actually using. The cancellation is the highest-use 30 minutes of the entire reset because the savings compound for as long as the accounts stay closed.
Step Three: Run a Zero-Based Plan for the Next 30 Days
Why 30 Days, Not the Whole Year
The next 30 days are the only window the brain can confidently predict. Beyond that, life shifts (rent increases, new subscriptions, a child’s activity changing) make longer-range budgets drift. The 30-day rolling plan is what stays current; the longer plan is what gets reviewed quarterly.
How to Build the 30-Day Plan
Expected income for the next 30 days. List every fixed expense. List the variable categories (groceries, transport, eating out, entertainment) with explicit caps. Add savings and debt acceleration. The total of all allocations should equal expected income (the zero-based principle).
If income exceeds the total, the excess goes to the current priority , emergency fund, debt, or specific savings goal. The weekly money reset guide covers the weekly tracking cadence inside the 30-day plan.
Step Four: Automate Every Fixed Transfer
Automation Beats Discipline
Discipline is unreliable across hard weeks. Automation runs regardless. Set up automatic transfers on payday for: savings (specific dollar amount), debt acceleration (specific dollar amount), and any sinking funds (social, Christmas, taxes for self-employed). The remaining balance becomes the spending account, and the spending happens within that container.
The Same-Day Rule
All automatic transfers run on the same day as payday , not three days later. Three days is enough for lifestyle expansion to absorb the money before the transfer happens. Same-day automation is the single highest-compliance financial habit in the personal-finance research.
The no spend month guide covers the 30-day intensive variant for households that need an additional reset on top of the standard automation.
Step Five: Name Three Specific Friction Points
Why the Friction Points Matter
Every household has two or three specific behaviors that drive most of the discretionary overspend. The 9 PM Amazon scroll. The Friday-night takeaway. The Sunday post-shopping coffee that turns into a $45 brunch. Naming the specific friction points is the diagnostic step that the budget alone does not produce.
How to Reduce the Friction
For each named friction point, design one specific intervention. Phone in another room after 9 PM. A weekly meal plan that covers Friday night. A Sunday plan that anchors on a free activity.
The interventions are small and specific. Most households reduce the named friction points by 50 to 80 percent within the first 90 days when the interventions are designed explicitly.
Step Six: Schedule the Weekly Review
The 60-Minute Sunday Slot
The reset is not a one-time event. The 60-minute Sunday review is what keeps the system honest. Same time each week. Same five steps each time: revisit goals, review the past week’s spending, categorize transactions, pay bills due in two weeks, celebrate one win. The cadence is what produces the long-term outcome.
Why Weekly Beats Monthly Maintenance
Monthly maintenance lets small overspends compound for three to four weeks before they get caught. Weekly catches the drift while it is in single digits. The cumulative effect across 12 months is the difference between year-end alignment and year-end surprise. The balance hustle and healing covers the broader sustainable-pace design the weekly review fits inside.
The 90-Day Outcome
What Changes by Day 30
Most households see measurable change by day 30: subscriptions cancelled, automation running, weekly slot held. The financial picture is not yet transformed but the system is in place. The control feels different even before the numbers shift.
What Changes by Day 90
By day 90, the system is running with less effort. The weekly review takes 40 minutes instead of 60. The friction points have measurably reduced. The automated transfers have produced a visible balance in savings or a visible drop in debt. The control has moved from the system to the lived experience of the household.
Frequently Asked Questions
What is a budget reset?
A budget reset is a 90-minute one-time setup followed by a 60-minute weekly maintenance cadence. Six setup steps: anchor to one emotional reason, list every account and subscription, run a zero-based plan for the next 30 days, automate every fixed transfer, name three friction points, schedule the weekly review.
Why systems instead of income?
Spirit Financial Credit Union’s 2026 debt-reset research finds that the difference between people who escape the debt cycle and people who stay stuck is systems, not income. Households without explicit budget systems run on reactive spending that scales with whatever is available; automated systems remove the daily decision-making where leakage usually happens.
How long does the setup take?
90 minutes for the initial setup, ideally on a single Sunday afternoon. The subscription audit alone usually surfaces $80 to $200 of monthly charges nobody is using. After setup, the maintenance is a 60-minute weekly slot.
What is a sinking fund?
A sinking fund is a separate small auto-transfer for a predictable irregular expense. Social spending. Christmas gifts. Taxes (for self-employed). The monthly amount adds up to the annual cost; the auto-transfer prevents the expense from feeling like an emergency when it arrives.
What if I miss the weekly review?
One missed week does not break the system. Two missed weeks is the warning sign that the slot is not protected enough. Resume the next Sunday. Most households who miss two weeks find the missed weeks correlate with the slot being scheduled at an unrealistic time; adjust the time before adjusting the habit.
How long until I feel in control?
Most households report a shift in felt control by day 30, before the numbers have measurably shifted. By day 90, the system is running with less effort, friction points have measurably reduced, and the savings balance or debt reduction is visible.
Key Takeaways
- Spirit Financial Credit Union 2026 research: the difference between households that escape the debt cycle and those that stay stuck is systems, not income.
- 6 setup steps: emotional anchor, full account inventory, zero-based 30-day plan, same-day automation, named friction points, weekly 60-minute review.
- Subscription audits usually surface $80 to $200 of monthly charges nobody is using , highest-use 30 minutes of the entire reset.
- Same-day automation (transfers on payday, not 3 days later) is the highest-compliance financial habit in the personal-finance research.
- By day 30 most households report a shift in felt control; by day 90 the system runs with less effort and measurable financial movement is visible.
Final Thoughts on the Budget Reset
A budget reset that actually gives you back control is six setup steps and a weekly slot. That is the whole thing. The 2026 research keeps landing in the same place: the households that recover are not the highest earners, just the ones with the cleanest systems.
Ninety minutes to set up. Sixty minutes a week to maintain. By day 90 you can feel the difference, and the rest of the year compounds quietly from there.
Last update on 2026-10-07 / Affiliate links / Images from Amazon Product Advertising API